Understanding IPI Before You Buy
When buying property in the Dominican Republic, understanding your annual ownership costs is an essential part of choosing the right investment. Alongside maintenance, insurance, and utilities, you should consider whether the property will create an annual real estate tax obligation.
The Dominican Republic’s Impuesto al Patrimonio Inmobiliario, commonly known as IPI, is an annual property tax. However, owning a home does not automatically mean you owe it. For individual owners, the calculation depends on the combined taxable value of their real estate and the exemptions that apply.
Here is how it works and what it could mean when purchasing a furnished apartment in Bávaro.
What Is IPI?
IPI is an annual tax administered by the Dirección General de Impuestos Internos (DGII), the Dominican tax authority.
It applies to taxable real estate held by individuals and trusts. Properties within its scope can include homes, urban land, and real estate used for commercial, industrial, or professional activities. . For individuals, the key consideration is the combined taxable value of their applicable real estate holdings. The exemption is applied to that combined amount, rather than separately to each property.
IPI in 2026
For the 2026 tax year, individuals benefit from an exemption threshold of RD$10,695,494. This amount is adjusted annually for inflation.
The annual tax rate is 1% of the taxable value exceeding that threshold.
The general calculation for an individual is:
Annual IPI = 1% × the amount by which taxable real estate holdings exceed RD$10,695,494.
If the combined taxable value falls at or below the threshold, no IPI is payable under this general rule. Trusts follow a different calculation: generally, the 1% rate applies to their total taxable real estate value, without the exemption threshold available to individuals. (dgii.gov.do)
Which Property Value Determines the Tax?
To establish your actual obligation, you need to verify the property’s value with the DGII. An asking price or agreed purchase price alone is insufficient to confirm the annual IPI.
The DGII provides a “Valor de Inmueble (IPI)” inquiry, and buyers can also seek guidance from the relevant local tax office. Reviewing this information before closing helps you budget using the applicable tax valuation.
When Is IPI Paid?
IPI is payable in two installments, with general deadlines of March 11 and September 11. The annual declaration must be submitted within the first 60 days of the year. When a payment deadline falls on a weekend or public holiday, it moves to the next business day.
Are There Additional Exemptions?
Certain owners and properties may qualify for additional benefits, subject to legal requirements. These include qualifying sole residences of owners over 65, benefits for qualifying foreign-source pensioners and passive-income recipients, agricultural properties, and certain tourism properties covered by special legislation.
Any benefit associated with CONFOTUR should be supported by the relevant documentation. A property’s location in Punta Cana or Bávaro does not establish eligibility on its own.
IPI and Property Transfer Tax Are Separate
An annual IPI obligation should be distinguished from the tax associated with purchasing and transferring a property.
As a general rule, property transfer tax is 3% of the higher of the contract sale price or the DGII valuation, unless an applicable exemption exists. A buyer may therefore have transfer tax to pay even when no annual IPI is due.
A Practical Example: A Furnished Apartment in CRISFER for US$115,000
https://elementrealtyrd.com/propiedad/2-bedroom-condo-for-sale-in-crisfer-punta-cana-airbnb-friendly-from-111500-1051?referer=314734
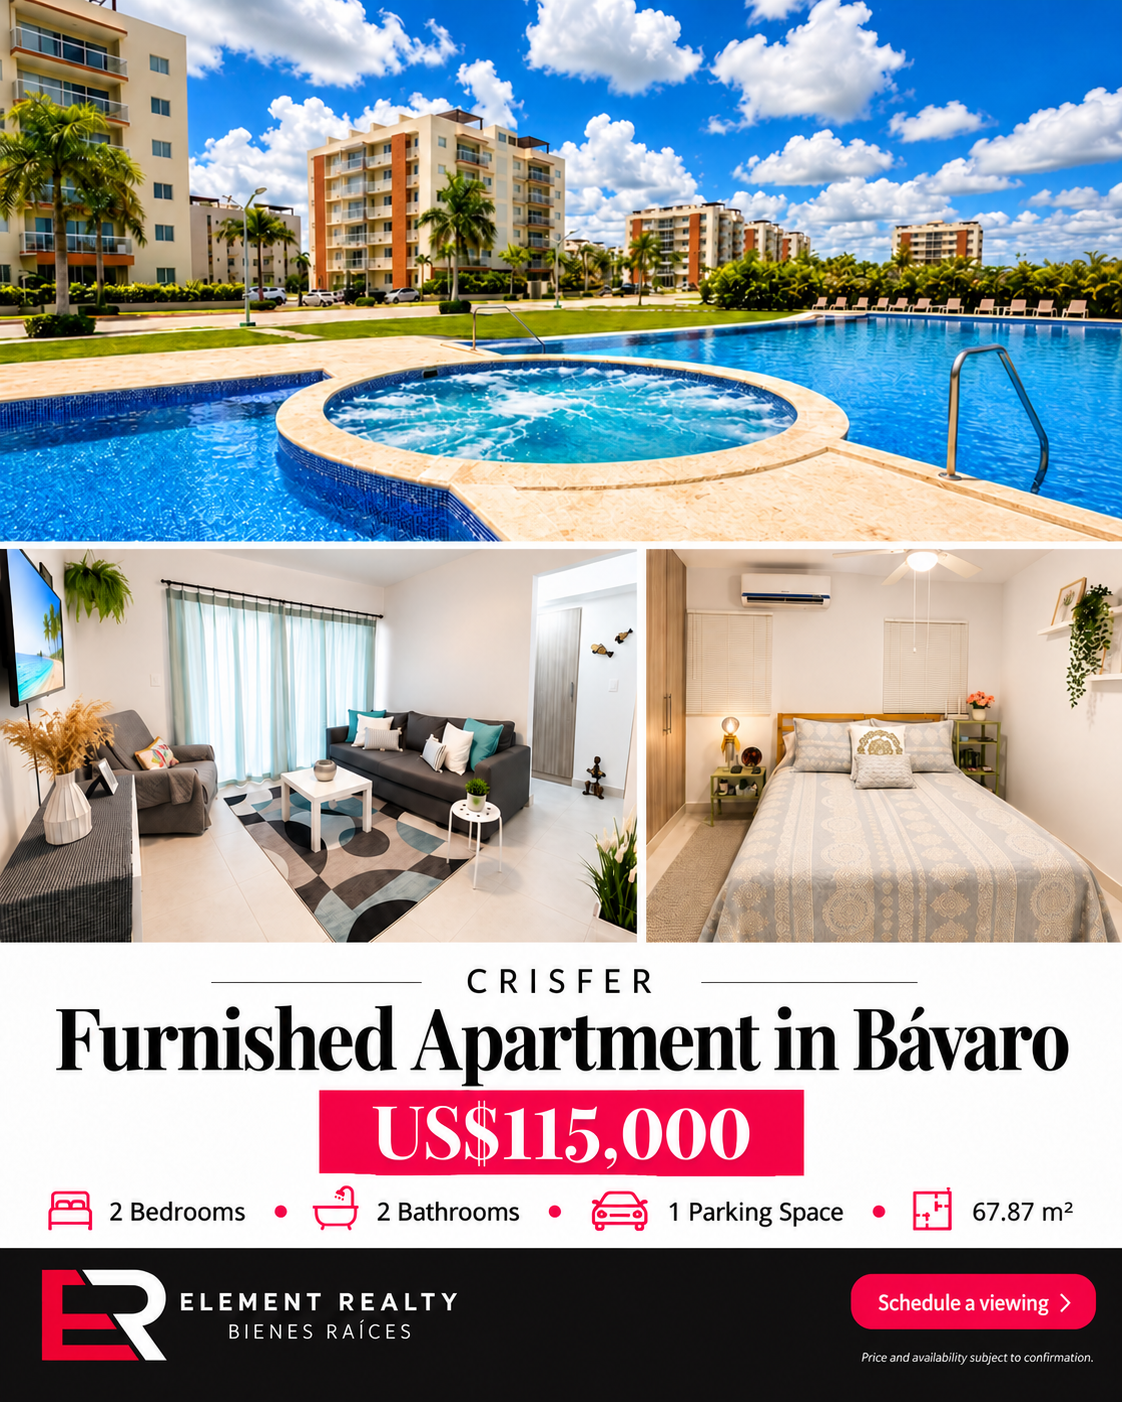
A Practical Example: A Furnished Apartment in CRISFER for US$115,000 Consider this furnished apartment in CRISFER, on Avenida Barceló in Bávaro, with an asking price of US$115,000, two bedrooms, two bathrooms, one parking space, and 67.87 m² of built area. How could IPI affect its ownership costs? Using an illustrative exchange rate of RD$60 per US$1, the 2026 individual exemption threshold is approximately US$178,258. If the DGII’s assessed value of the apartment were equivalent to US$115,000 and the buyer owned no other taxable real estate in the Dominican Republic, the property would fall below that threshold, resulting in US$0 in annual IPI under these assumptions. For a buyer considering a furnished home in Bávaro, this could help keep annual ownership expenses more manageable, alongside maintenance, insurance, and utilities. However, buyers who already own other taxable properties must consider their combined assessed value. For example, if the buyer held another US$100,000 in taxable real estate, their combined holdings would total US$215,000. After deducting the illustrative exemption equivalent of US$178,258, approximately US$36,742 would be subject to the 1% rate, producing an annual IPI equivalent to approximately US$367.42 on the combined holdings. These dollar amounts explain a tax calculated and payable in Dominican pesos; the exchange rate is hypothetical, and the apartment’s actual DGII valuation must be verified. With its furnished interior and two-bedroom layout, this CRISFER apartment is an option to explore for your next property purchase in Bávaro. Contact Element Realty to confirm its current price and availability, request the complete property details, and arrange a viewing.
Consider this furnished apartment in CRISFER, on Avenida Barceló in Bávaro, with an asking price of US$115,000, two bedrooms, two bathrooms, one parking space, and 67.87 m² of built area. How could IPI affect its ownership costs? Using an illustrative exchange rate of RD$60 per US$1, the 2026 individual exemption threshold is approximately US$178,258. If the DGII’s assessed value of the apartment were equivalent to US$115,000 and the buyer owned no other taxable real estate in the Dominican Republic, the property would fall below that threshold, resulting in US$0 in annual IPI under these assumptions. For a buyer considering a furnished home in Bávaro, this could help keep annual ownership expenses more manageable, alongside maintenance, insurance, and utilities. However, buyers who already own other taxable properties must consider their combined assessed value. For example, if the buyer held another US$100,000 in taxable real estate, their combined holdings would total US$215,000. After deducting the illustrative exemption equivalent of US$178,258, approximately US$36,742 would be subject to the 1% rate, producing an annual IPI equivalent to approximately US$367.42 on the combined holdings. These dollar amounts explain a tax calculated and payable in Dominican pesos; the exchange rate is hypothetical, and the apartment’s actual DGII valuation must be verified. With its furnished interior and two-bedroom layout, this CRISFER apartment is an option to explore for your next property purchase in Bávaro.
Contact Element Realty to confirm its current price and availability, request the complete property details, and arrange a viewing.
Tax information relates to 2026. Examples are illustrative; the actual tax obligation must be verified with the DGII. Property pricing and availability are subject to confirmation.